Insurance Agency in Houston, Texas
Auto, home and business coverage for Houston, quoted by phone. Harris County rating, TWIA wind, NFIP flood. Wind stays on the home policy west of SH 146.
Aulona Insurance Group is an independent insurance agency licensed in Texas (Agency License #3481412) with an office in Plano. Luka Cenaj, a licensed Texas agent, is the reviewer of record for every coverage page on this site.
Texas Agency License #3481412 · NPN 22184980 · English & Albanian
On this page7 sections
Auto, home and business coverage for Houston
Aulona Insurance Group places auto, home and small-business coverage on a Houston address, all three on the same call instead of in three sales conversations.
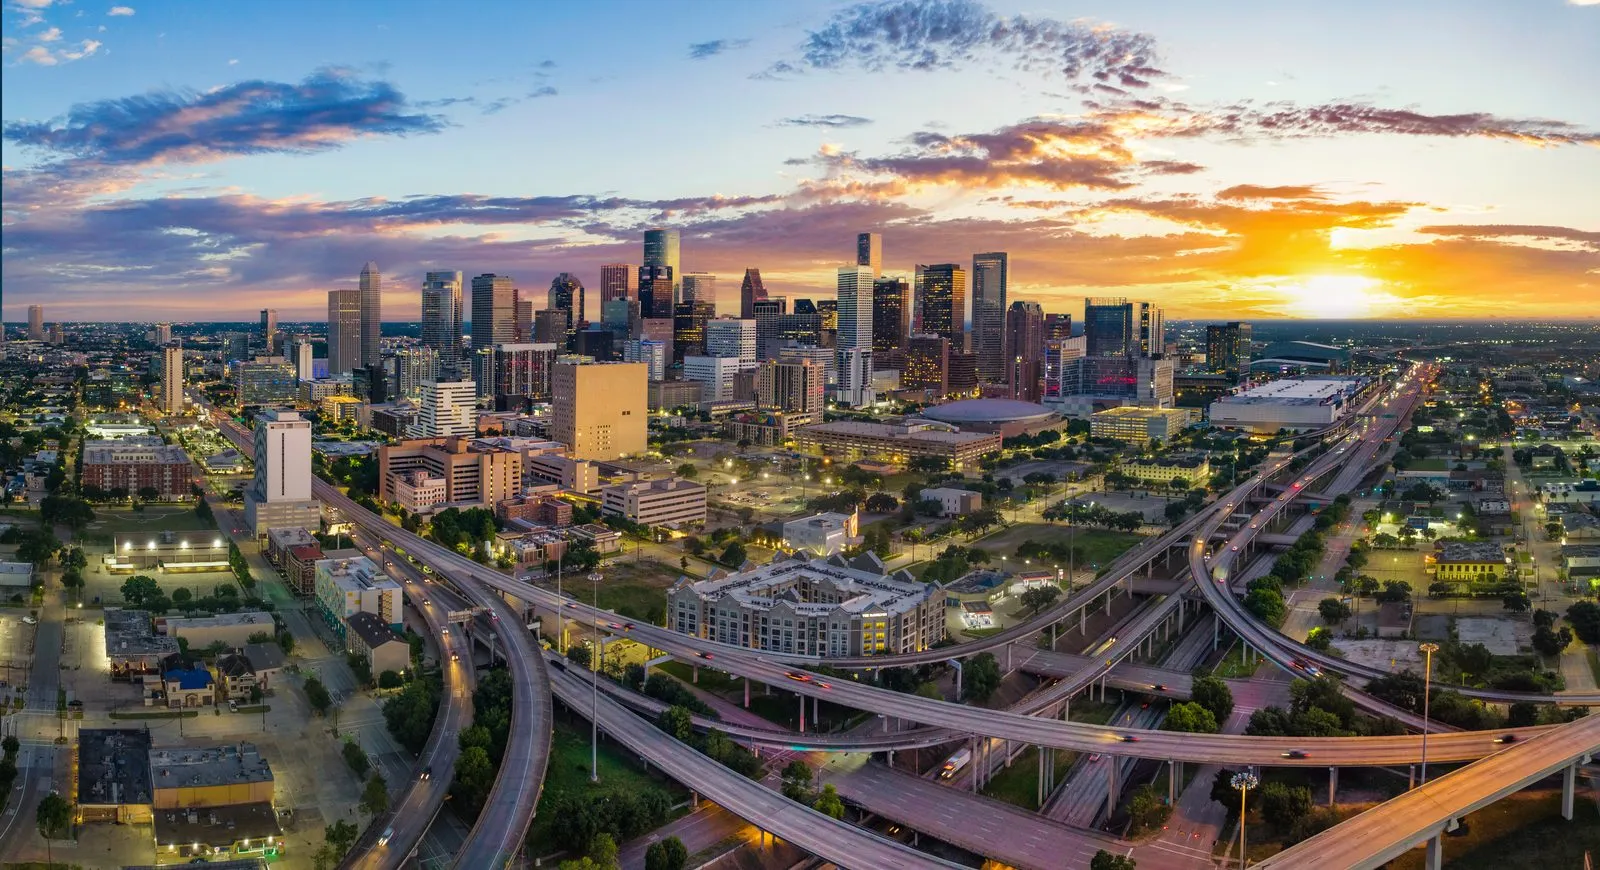
Houston sits mostly in Harris County, with city limits reaching Fort Bend and Montgomery County, and a Texas homeowners policy excludes flood everywhere and windstorm in parts of Harris County, so water and wind get settled separately.
Service is by phone from the one office, in Plano, and no visit to Houston or to Plano is part of placing coverage. No Houston quote is issued and nothing is bound before a recorded call with Luka Cenaj, in English or Albanian.
Auto insurance in Houston
Auto insurance in Houston starts at the liability floor Texas sets statewide, written as 30/60/25 (Texas Transportation Code §601.072): $30,000 for injury to one person, $60,000 for injuries in one accident, $25,000 for damage to another person’s property.
Houston sits mostly in Harris County and the city limits also reach Fort Bend County and Montgomery County, per the City of Houston.
Vehicle theft is the Houston claim that sets the city apart. The Texas Department of Public Safety publishes a monthly auto theft report built from Texas Crime Information Center entries, and the Houston Police Department reports into it.
Theft and flood water are both comprehensive claims, subject to the deductible on that coverage.
Home insurance in Houston
Home insurance in Houston is built around water and wind: a Texas homeowners policy excludes flood everywhere and, on part of Harris County, windstorm as well.
Three things a Houston homeowner sorts out separately:
- Flood goes through the National Flood Insurance Program, and a new NFIP policy has a 30-day waiting period
- Parts of Harris County east of Hwy 146 sit in Texas Windstorm Insurance Association territory (Texas Insurance Code ch. 2210), where wind and hail sit on a TWIA policy
- Tropical storm, hurricane and flash flood warnings come from the National Weather Service Houston/Galveston office
Aulona Insurance Group places coastal homeowners and dwelling coverage in the Tier 1 and Tier 2 coastal counties, with windstorm through the Texas Windstorm Insurance Association inside the designated catastrophe area and flood through the National Flood Insurance Program. Dwelling fire, condo and renters, landlord DP-1 and DP-3 and personal umbrella coverage above the home and auto liability limits are also placed.
Business insurance in Houston
Aulona Insurance Group places small commercial for Houston businesses: a business owners policy (BOP), general liability, commercial property, workers compensation, professional liability, umbrella and excess, and commercial auto.
The program has hard eligibility limits, and a Houston business outside them has no market here:
- Annual gross revenue under $5 million, and total W-2 payroll under $5 million
- Workers compensation runs through its own market and is not limited by the revenue and payroll figures above
- Each location needs its own BOP, and a BOP caps at $5 million of total insured value
A Houston account also needs a loss history under $20,000, no more than two incidents in three years, and no prior carrier cancellation or bankruptcy filing.
Restaurants and the rest of food and beverage are the classes that place most readily, followed by professional services, personal care, retail and technology services. Business Insurance in Houston, Texas goes through the classes.
Where Aulona Insurance Group is not the right fit
Aulona Insurance Group turns away a real share of Houston calls, and two limits account for most of them.
- Night clubs, gas stations and towing operators, with no market on the agency’s package lines
- Roofing and siding contractors, however small the crew, with no market on the agency’s package lines
The rest of the no-market classes and size limits are listed once, on the agency page, and they bind a Houston account the same way. Life, health, Medicare and disability are not written for Houston on any basis.
What moves the price of a Houston policy
A Houston premium is set by the insurer that writes the policy, and Aulona Insurance Group publishes no figure for one.
The Harris, Fort Bend or Montgomery County territory the vehicle garages in matters, along with the miles it runs from there and the driving record behind the wheel.
On property, the FEMA flood map zone prices a National Flood Insurance Program policy, a Texas Windstorm Insurance Association policy east of Hwy 146 carries its own windstorm deductible, and roof age and construction are read on the homeowners form. Class code first, then payroll, revenue and loss runs, is how a commercial account is priced.
Working with Aulona Insurance Group from Houston
Houston’s Harris County territory lies west of Highway 146, and Highway 146 is the eastern edge of the area the Commissioner of Insurance has designated for the Texas Windstorm Insurance Association. Wind and hail on a Houston house therefore stays on the homeowners or dwelling fire policy instead of going to TWIA.
- Answer the eight questions on the quote form, about two minutes, ending with a one-time code texted to your mobile, or leave a Houston number on the contact page.
- Take the recorded call from Luka Cenaj, who works through the drivers, the Houston address and the operation behind it.
- Leave the Houston risk with Aulona Insurance Group to place with the insurers it holds appointments with.
What happens when you contact us
Callback, call, placement. No pricing is shown before a licensed agent has spoken with you.
Request a callback
Leave a number and a good time on the contact page, or call the agency directly. We text a code to confirm your number.
A licensed agent calls you
Luka goes through coverage and your situation. No pricing is shown before that call.
Coverage gets placed
We go to the markets we hold appointments with and tell you plainly if we are not the right fit.
This page covers one part of Independent Insurance Agency Serving 50 Texas Cities.
Related
