Does Home Insurance Cover a Roof?
Whether a roof claim is paid usually comes down to cause and age. Actual cash value versus replacement cost, and what Texas hail policies do.

Aulona Insurance Group is an independent insurance agency licensed in Texas (Agency License #3481412) with an office in Plano. Luka Cenaj, a licensed Texas agent, is the reviewer of record for every coverage page on this site.
Texas Agency License #3481412 · NPN 22184980 · English & Albanian
On this page6 sections
Cause and age decide a roof claim
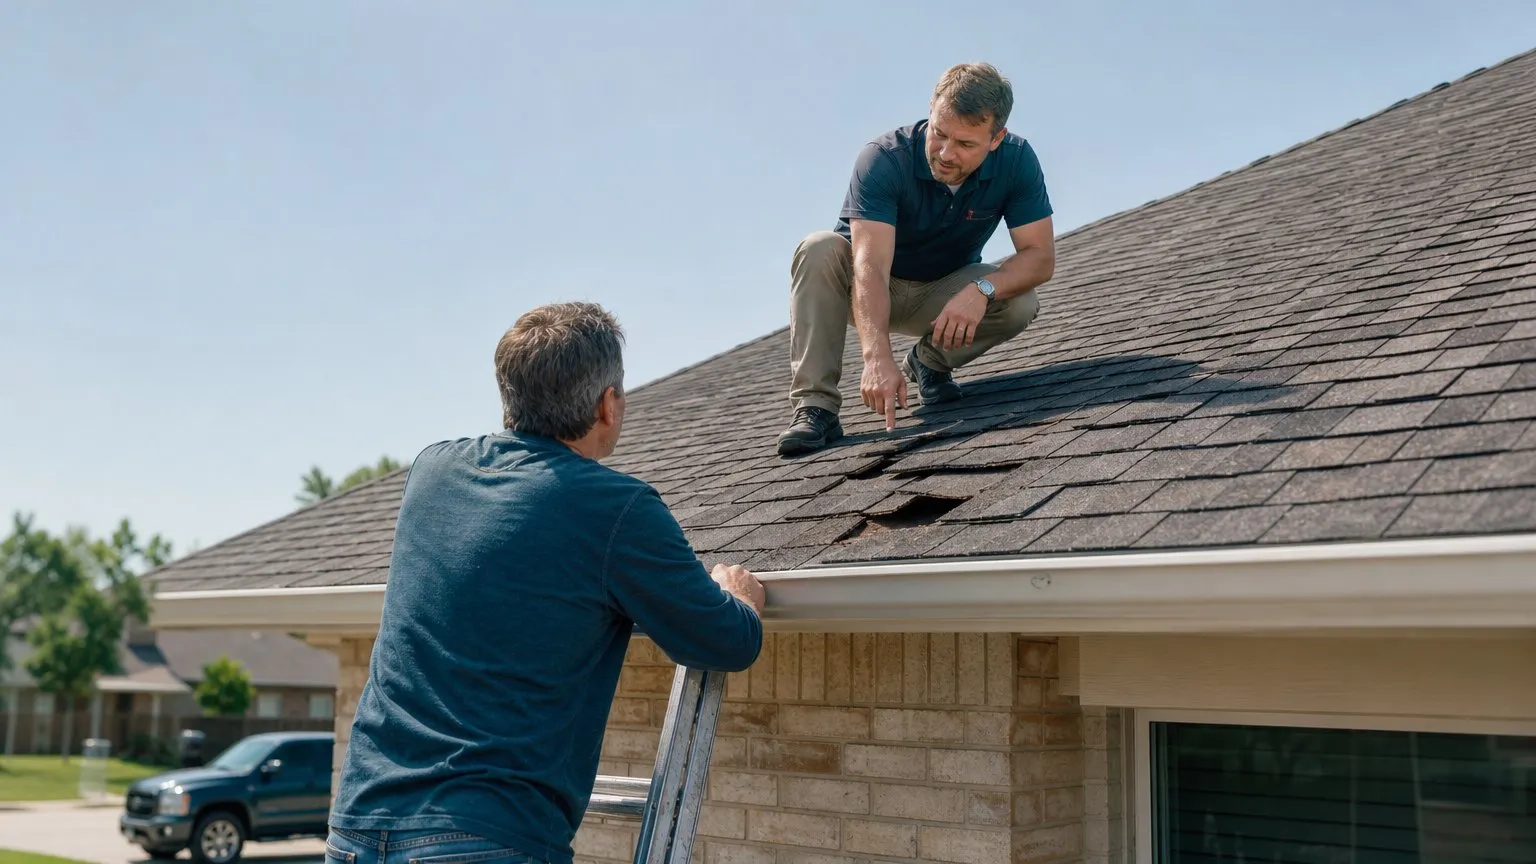
A Texas homeowners form pays for a roof damaged by a sudden event and excludes a roof that wore out. Hail, straight-line wind, a falling tree and fire are covered causes on a standard homeowners policy, subject to the deductible and any roof endorsement. Age, deterioration, poor installation and a leak that has been running for months are excluded.
Two questions decide a roof claim, and they get answered in order. Cause decides whether the claim is paid at all. Age decides how much of it gets paid, because an older roof can settle at actual cash value instead of replacement cost.
Read the declarations page before the roof is ever damaged. Both answers are printed there, in the deductible line and in the endorsement list.
How a roof claim is settled
Replacement cost pays what a new roof of like kind and quality costs today. Actual cash value pays that figure minus depreciation for the roof’s age and condition, and on a roof most of the way through its life the depreciation is the larger half.
Four settlement terms decide the payment:
- Replacement cost arrives in two parts, an actual cash value payment first and the withheld depreciation after the work is finished and invoiced
- Actual cash value arrives once, and the homeowner funds the difference
- A roof payment schedule endorsement, where a policy carries one, steps the settlement down by the roof’s age and its roofing material
- A cosmetic damage exclusion removes dents and marring that do not let water in, which bites hardest on metal roofing
Which of those applies is written on the policy, not decided at the claim.
What a homeowners policy excludes on a roof
Exclusions decide as much of a roof claim as the covered perils do. A roof that fails gradually falls outside a homeowners policy, which pays for sudden loss.
Excluded on a standard form:
- Wear, tear, marring, and deterioration, however visible the damage is
- Faulty workmanship, defective materials, and a roof installed wrong
- Continuous or repeated seepage of water over weeks or months
- Damage to a roof that was already in disrepair when the policy was written
- Neglect, meaning failure to protect the roof from further damage after a loss
Resulting damage is the exception worth knowing. A policy that excludes the faulty installation can still pay for the ceiling and the flooring the water ruined on its way through.
The Texas version
Texas homeowners policies split hail out from everything else. The Texas Department of Insurance home insurance guide describes a separate wind and hail deductible written as a percentage of the dwelling limit rather than as a flat amount, so the deductible climbs every time the policy renews at a higher replacement cost.
Texas coastal counties move the peril off the policy entirely. The Texas Windstorm Insurance Association (TWIA) writes windstorm and hail under Texas Insurance Code ch. 2210 for the 14 first-tier coastal counties and the part of Harris County east of Highway 146, and a homeowners policy written there can exclude the peril in favor of that TWIA coverage.
The Texas Department of Insurance answers questions about roof settlements and takes complaints at 1-800-252-3439 and at tdi.texas.gov.
Aulona Insurance Group places the coverage this question is about: Texas Home Insurance.
What pays and what does not on a Texas roof
Cause of loss is the first column. The table gives the usual answer on a standard Texas homeowners form.
| Cause of the roof damage | Covered | How it usually pays |
|---|---|---|
| Hail | Yes | Wind and hail deductible applies |
| Straight-line wind or a named storm | Yes inland, via TWIA on the coast | Wind and hail deductible |
| A tree falling on the roof | Yes | All other perils deductible, plus debris removal |
| Fire or lightning | Yes | Replacement cost, where the form provides it |
| Shingles at the end of their service life | No | Wear and tear excluded |
| A leak that has run for months | No | Continuous seepage excluded |
| Faulty installation by a roofer | No | Resulting water damage can still be covered |
| Dents in metal panels that still shed water | Depends | A cosmetic damage exclusion removes them |
Roof age sits behind the rows: past its service life, a covered cause still pays little.
What to have ready before you ask an agent
Find the roof’s age first. Every other answer about a Texas roof claim moves once an underwriter knows the year the covering was installed, and a guess produces a quote that changes later.
Gather these before the call:
- The year the roof was last fully replaced, and whether that replacement was paid by a claim
- The declarations page, showing the wind and hail deductible and any roof endorsement
- Photographs of every slope, taken from the ground
- The roofing material, the roof’s pitch, and the number of layers
- The county, because the county and the distance to the coast are the first rating inputs
Aulona Insurance Group cannot place a Texas home that has to go to surplus lines, and preferred inland owner-occupied homeowners in the DFW suburbs is a weak market for the agency. Luka Cenaj says so before the application rather than after it.
What happens when you contact us
Callback, call, placement. No pricing is shown before a licensed agent has spoken with you.
Request a callback
Leave a number and a good time on the contact page, or call the agency directly. We text a code to confirm your number.
A licensed agent calls you
Luka goes through coverage and your situation. No pricing is shown before that call.
Coverage gets placed
We go to the markets we hold appointments with and tell you plainly if we are not the right fit.
Related
